This is an independent academic submission by Eng NM Kazembe, a mining project engineer pursuing a Doctor of Business Administration (DBA) degree under Unicaf University. It does not represent the position of any employer, the Government of Zambia, the Zambia Revenue Authority, any mining company, bank, or any other institution.
8 November 2026 | 11:46 CAT
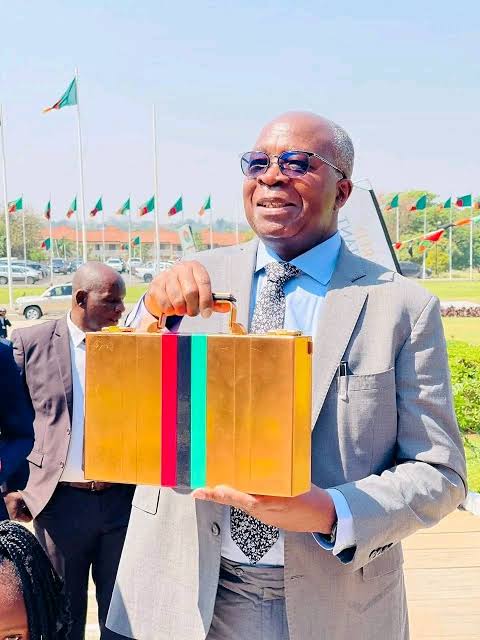
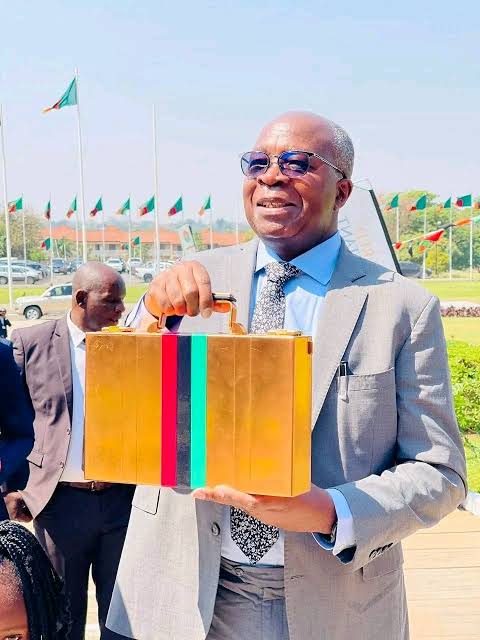
The 2027 National Budget, presented by Finance and National Planning Minister Dr Situmbeko Musokotwane on 6 November 2026, has predictably drawn criticism. The K284.8 billion budget introduces a new top Pay-As-You-Earn (PAYE) marginal rate of 39.5% on monthly income above K37,000 and raises the standard VAT rate from 16% to 16.5%. These measures are projected to raise an additional K10.8 billion in revenue.
Many voices have framed the Zambia Revenue Authority and Ministry of Finance as the villains squeezing the private sector. A closer look at the numbers and recent labour market developments suggests a more nuanced picture. The government is responding to fiscal needs and macroeconomic realities that include wage growth in high-earning sectors that has outpaced broader productivity gains in places.
Recent Wage Settlements in Mining and Banking
Mining remains Zambia’s economic backbone. Over the past year, several major operators reached collective agreements delivering double-digit salary increases for unionised workers:
• Konkola Copper Mines awarded a 13% increment for 2026 (on top of a prior 20% rise in mid-2024).
• Mopani Copper Mines settled on a 12% increase.
• Lumwana Copper Mines (Barrick) agreed a 13% rise.
• Kagem Mining committed to 10% in 2026 and another 10% in 2027.
The banking sector provides clear outliers of similarly aggressive settlements. Zanaco awarded a 15% salary increase to unionised staff for 2026. Absa Bank Zambia granted a 14% rise covering 2025–2026. FNB Zambia concluded a 2026/2027 agreement delivering an average 11.4% increase (with earlier cycles reaching higher single-year figures). First Capital Bank secured a settlement reported at approximately 15.8%. These banking awards sit well above prevailing inflation and inject additional high-end purchasing power into the formal economy, particularly in Lusaka and other urban centres.
These settlements reflect legitimate union pressure and the need to retain skills in competitive sectors. They also inject substantial additional kwacha into the market. When wage growth significantly exceeds national productivity or sectoral output growth, the extra purchasing power can contribute to localised and broader price pressures — even if national inflation remains contained.
The Case for CPI-Linked Wage Adjustments
A more disciplined approach to wage setting would anchor increments to the Consumer Price Index (CPI) rather than purely to union bargaining power or short-term company profitability. CPI provides an objective, economy-wide measure of the cost-of-living pressures that workers actually face. Linking wage growth primarily to CPI (with modest productivity add-ons where justified) would help prevent the creation of artificial liquidity bubbles in high-wage sectors while still protecting real incomes. When settlements in mining and banking repeatedly exceed CPI by a wide margin without corresponding gains in output or efficiency, the resulting excess demand spills into the broader economy and eventually forces fiscal responses such as the 2027 tax adjustments.
The Macro Context
Zambia’s inflation picture has improved markedly. Annual inflation stood at around 6.3% in October 2026, well below the double-digit rates of previous years and inside or near the Bank of Zambia’s target band. Copper production reached a record 890,346 tonnes in 2025 and is projected near 930,000 tonnes in 2026, though the ambitious 3-million-tonne target by 2031 remains distant.
Wage increases that outrun underlying output gains still matter. Excess liquidity in high-wage sectors can spill into demand for imports (machinery, consumer goods, processed foods), putting pressure on the exchange rate and raising the cost of living for workers outside those sectors. The government faces the classic policy choice of allowing potential demand-pull effects to run or using fiscal tools to moderate them.
How the 2027 Tax Measures Fit
The new PAYE structure is explicitly progressive. The minister has stressed that earners at or below K37,000 per month continue under the existing bands (0% up to K5,100, then 20%, 30% and 37%). Only the slice of income above K37,000 faces the 39.5% rate.
The half-percentage-point VAT increase broadens the consumption tax base. Together with other measures — including a 15% withholding tax on mining dividends (previously zero) and adjustments to corporate rates on lower-taxed income — the package aims to raise domestic revenue while protecting lower and middle earners.
Broadening the Tax Base: A Valid Goal with Practical Instruments
The argument for broadening Zambia’s tax base is sound. A narrow formal-sector tax base places heavy pressure on a relatively small group of salaried workers and registered companies. In this context, the modest VAT increase and the higher levies on mobile-money transactions serve a useful complementary purpose: they help capture economic activity among the unbanked and those operating largely outside the formal tax net. Mobile-money platforms have become a major channel for everyday transactions across both urban and rural Zambia. Raising the transaction levies on these platforms brings previously hard-to-tax informal flows into the revenue system without requiring complex new compliance infrastructure. While no tax instrument is perfect, these measures represent pragmatic tools for expanding the tax net in an economy where large segments of activity remain cash- or mobile-based and under-taxed.
These are not drastic “hikes” in the sense of broad-based rate jumps. They are targeted adjustments that capture a larger share of income at the upper end of the distribution and of spending that has been supported, in part, by recent corporate wage decisions in mining and banking.
How Zambia Compares within SADC
Zambia’s 2027 changes place it in the upper half of the Southern African Development Community for both personal income tax and consumption tax, but not at the extreme.
Top Marginal Personal Income Tax Rates (approximate 2026/27)
South Africa leads the region at 45%. Zambia’s new 39.5% rate (applied only above K37,000 per month) sits close to Zimbabwe and above Namibia (~37%), Malawi (~35%), Mozambique (32%), Tanzania (30%) and Botswana (27.5%). Mauritius remains significantly lower. The Zambian rate is therefore high by regional standards, yet still below the South African ceiling and narrowly targeted.
Standard VAT Rates
Zambia’s move to 16.5% aligns it with Malawi at the higher end of the SADC range. Tanzania sits higher still at 18%. Most larger economies (South Africa, Namibia, Zimbabwe) remain at 15%, while Botswana and Angola are lower at 14%. The half-percentage-point increase therefore moves Zambia into the higher-tax group on consumption as well as on high-end personal income.
Tax Revenue and Public Value: The Delivery Gap
Raising more revenue is only half the equation. Citizens ultimately judge the legitimacy of higher taxes by the quality of services they receive in return. Across SADC, performance varies markedly.
Relatively stronger performers
Mauritius, Botswana, Seychelles and (to a lesser extent) Namibia consistently score higher on government effectiveness, lower perceived corruption, and better human-development outcomes relative to the taxes they collect. Botswana in particular combines relatively moderate tax rates with stronger institutional performance and lower everyday leakage.
Weaker value-for-money performers
Most other SADC countries, including Zambia, still face a noticeable disconnect between formal-sector tax contributions and the quality of frontline services. World Bank Government Effectiveness scores, Transparency International Corruption Perceptions Index rankings, Human Development Index positions, and citizen surveys (including Afrobarometer-style data) all point to persistent dissatisfaction with water and sanitation, healthcare, electricity reliability, road maintenance and local government responsiveness. Formal-sector taxpayers frequently feel they subsidise a system that under-delivers.
Shared Responsibility and a Call for Accountability
It is inaccurate to portray the government as the sole driver of higher taxes. Corporate boards and management teams — whether in mining houses or commercial banks — that approve large wage settlements without corresponding productivity or output gains help create the conditions in which fiscal authorities feel compelled to act. At the same time, workers in these high-wage sectors have legitimate claims to share in institutional returns, and unions have successfully negotiated better conditions after years of pressure.
The healthier path forward is alignment: wage growth that tracks sustainable productivity, sectoral output and the CPI, paired with a tax system that remains progressive, predictable and deliberately broader in its reach. Equally important is that every business — formal or informal — that generates economic activity should hold a valid Tax Payer Identification Number (TPIN) and contribute its fair share. Broadening the base cannot succeed if large segments of commercial activity remain outside the tax net.
Ultimately, the onus rests on government to pull up its socks on service delivery and accountability. From the ward level and Constituency Development Fund (CDF) projects, through district and provincial administration, all the way to the highest offices of state and the management of macroeconomic policy, public resources must demonstrably improve the daily lives of citizens. Higher tax rates will only retain legitimacy if taxpayers can see tangible returns — reliable water, functioning health facilities, maintained roads, consistent electricity, and transparent local development. Without that visible link between revenue raised and services delivered, the social contract frays. Zambia’s formal-sector taxpayers, mining communities and banking employees are entitled to demand nothing less.
This submission reflects the independent analysis and academic perspective of Eng NM Kazembe, a mining project engineer pursuing a Doctor of Business Administration (DBA) degree under Unicaf University. It is not an official position of any employer, government body, mining company, bank, or other institution.
References
Budget and Tax Measures
Lusaka Times. (2026, November 7). Here is who pays more under Zambia’s 2027 budget tax measures. https://www.lusakatimes.com/2026/11/07/here-is-who-pays-more-under-zambias-2027-budget-tax-measures/
Lusaka Times. (2026, November 6). Musokotwane presents K284.8 billion 2027 budget. https://www.lusakatimes.com/2026/11/06/musokotwane-presents-k284-8-billion-2027-budget/
Zambia Monitor. (2026, November 7). Some takeaways from proposed 2027 budget — Lubinda. https://www.zambiamonitor.com/some-takeaways-from-proposed-2027-budget-lubinda/
Zambia Revenue Authority. (2026). 2027 Budget Highlights. https://www.zra.org.zm/wp-content/uploads/2026/11/2027-Budget-Highlights-1.pdf
Reuters. (2026, November 6). Zambia sees steady growth and smaller budget deficit next year. https://www.reuters.com/world/africa/zambia-aims-49-growth-3-gdp-budget-deficit-2027-2026-11-06/
Mining Sector Wage Settlements
Zambia Monitor. (2026, January 31). KCM reportedly awards workers 13% salary increase. https://www.zambiamonitor.com/kcm-reportedly-awards-workers-13-salary-increase/
ZNBC. (2026, February 10). Mopani Copper Mine workers get 12% salary increase. https://znbc.co.zm/?p=11047
IndustriALL Global Union. (2026, February 3). MUZ wins wage deal from Lumwana, demands more for Zambian communities. https://www.industriall-union.org/muz-wins-wage-deal-from-lumwana-demands-more-for-zambian-communities/
Miners Digest. (2026, January 19). Kagem agrees to 10% salary increase in 2026/27. https://minersdigest.com/news/kagem-agrees-to-10-salary-increase-in-2026-27/
Banking Sector Wage Settlements
Zambian Business Times. (2026, September 9). FNB employees to get 11% salary increase. https://zambianbusinesstimes.com/fnb-employees-to-get-11-salary-increase/
Efficacy News. (2026, January 22). ZUFIAW announces 15% pay rise for Zanaco employees. https://efficacynews.africa/2026/01/22/zufiaw-announces-15-pay-rise-for-zanaco-employees/
ClickPlus Business. (2025, December 10). ABSA Bank Zambia signs new wage deal, grants 14% salary increase to unionised staff.
Macroeconomic Indicators & Regional Comparisons
Financial Insight Zambia. (2026, November 8). October 2026 inflation and trade statistics update.
Zambia Monitor. (2026, November 7). Zambia targets record copper output, maintains stable mining tax regime.
Transparency International. (2026). Corruption Perceptions Index 2025.
World Bank. (2026). Worldwide Governance Indicators – Government Effectiveness.
United Nations Development Programme. (2025). Human Development Report 2025.
Harvester Online. (2026). Zambia PAYE tax rates 2027, 2026 & 2025. https://www.harvesteronline.net/zambia-paye-tax-rates.php